Top High Yield Savings Account Options for 2026
The best high-yield savings account in 2026 is one that pays a competitive variable APY on the day you open it, charges no monthly fee you would actually trigger, and sits at an FDIC-insured bank or a federally insured credit union. Advertised yields move often, so this guide deliberately does not print a rate table that would be out of date within weeks. Instead it shows how to read a bank's rate page, which fees and limits to look up, and how deposit insurance really works. As a reference point, the FDIC's national average rate for savings accounts was 0.37% in its September 2026 release (FDIC, National Rates and Rate Caps, published September 21, 2026). Online accounts that advertise several times that figure are the ones worth comparing; an account paying close to the national average is not a high-yield account, whatever its name says.
Key Facts:
- Savings rates are variable. The APY on the bank's rate page today is not a promise for the rest of the year.
- FDIC insurance covers $250,000 per depositor, per FDIC-insured bank, for each account ownership category (FDIC, page last updated April 1, 2024).
- Federally insured credit unions carry the same $250,000 standard through the NCUA Share Insurance Fund (NCUA, Share Insurance Coverage page).
- The Federal Reserve removed the six-per-month transfer limit from the Regulation D savings definition on April 24, 2020, but each bank can still set its own withdrawal limits and fees.
- If a bank pays you $10 or more of interest in a year, expect a Form 1099-INT (IRS Tax Topic 403).
What Interest Rates Do High Yield Savings Accounts Offer?
Online savings rates tend to follow the direction of the Federal Reserve's policy rate, but each bank decides when and how far to move its own APY. That is why two accounts that paid the same rate in spring can be far apart by autumn. The only reliable number is the one on the bank's own rate page on the day you compare, so write it down with the date next to it. APY already includes the effect of compounding, which makes it the right figure for comparing accounts; the "interest rate" shown beside it is the figure before compounding. A rough way to estimate a year's earnings is balance × APY: a $10,000 balance at a hypothetical 4% APY would earn about $400 over twelve months if the rate never changed and no money moved in or out. Real results differ because the rate will change. Before you move money, check three things on the rate page: whether the advertised rate is an introductory rate with an end date, whether it applies to your whole balance or only up to a cap, and whether it requires a direct deposit, a minimum monthly deposit or a linked checking account.
After the account is open, read the monthly statement once in a while and compare the interest credited with what the posted APY and your average balance would suggest. If the figure is clearly lower, the rate may have changed, a balance tier may apply, or a promotional period may have ended. Check whether the bank pays its top rate on every dollar or only up to a balance cap; a rate that stops at a cap matters most for an emergency fund that keeps growing. Taxes are the other part of the real return. The IRS treats most interest credited to an account you can withdraw from without penalty as taxable income in the year it becomes available, and a payer that pays you $10 or more of interest should send Copy B of Form 1099-INT (IRS Tax Topic 403). You still report interest below that amount even if no form arrives. Your after-tax yield therefore depends on your own bracket, which is one more reason to compare accounts on the posted APY rather than on a headline in an ad.
What Are the Hidden Fees and Minimums?
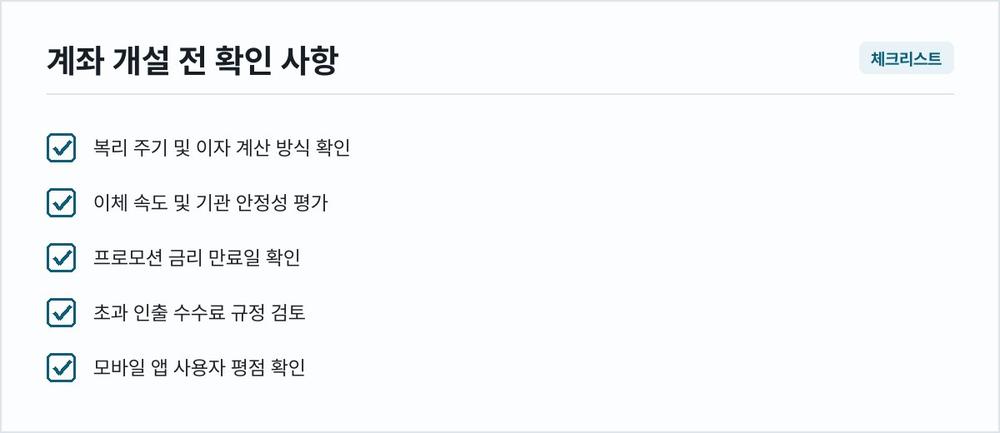
"No monthly fee" on the landing page does not mean the account has no fees. The place to look is the bank's fee schedule or deposit account agreement, usually linked at the bottom of the account page. Read it for the charges that would actually apply to how you use savings: outgoing wire transfers, expedited or paper checks, paper statements, excess withdrawals, and inactivity or dormancy. Opening requirements also differ: some banks open an account with no deposit, while many credit unions ask for a small share purchase to establish membership. Look up the exact figure on the institution's own page rather than relying on a comparison site, because these amounts change without notice.
Withdrawal limits deserve a separate look. On April 24, 2020, the Federal Reserve Board issued an interim final rule deleting the six-per-month limit on convenient transfers from the Regulation D definition of a savings deposit, which allowed banks to stop enforcing it (Federal Reserve press release, April 24, 2020). The rule change allows unlimited transfers; it does not require them. Some banks kept a monthly cap and charge a fee or convert the account when you exceed it, so find the "transactions" or "withdrawal limits" section of the agreement. Finally, check what happens to an account that sits unused: dormancy rules can lead to fees, closure, or the balance being turned over to the state as unclaimed property. A short, written checklist of these items, filled in from each bank's own documents, is the most useful comparison you can make.
How Do Deposit Insurance and Safety Work?
Safety of principal is the reason to hold cash in a savings account at all. The FDIC insures deposits at $250,000 per depositor, per FDIC-insured bank, for each account ownership category; deposits in the same category at the same bank are added together (FDIC, Understanding Deposit Insurance, last updated April 1, 2024). Different categories are insured separately: the FDIC's own example is a person with a single account and a joint account at one bank, who is insured up to $250,000 for the single account and separately up to $250,000 for their ownership interest in the joint deposits. Credit unions follow the same pattern through the NCUA: single accounts are insured up to $250,000 per member-owner and a member's interest in all joint accounts combined up to $250,000 (NCUA, Share Insurance Coverage).
Two practical checks follow. First, confirm that the company holding your money is itself an insured bank, or that it names the insured partner bank where the deposit actually sits; the FDIC's BankFind tool and the NCUA's credit union locator let you look up the charter. Some apps spread one customer's balance across several partner banks; in that case ask for the list of banks, because coverage depends on how much lands at each one and on any money you already hold there. Second, know your protection against fraud. Under Regulation E (12 CFR 1005.6), if you notify the institution within two business days after learning that your card or other access device was lost or stolen, your liability for unauthorized transfers is capped at the lesser of $50 or the amount taken before notice; after that window the cap rises to as much as $500 under the same section. Turn on two-factor sign-in, set up transfer alerts, and report anything unusual the same day.
What Is the Transfer and Access Speed?
Money leaves a high-yield savings account in three main ways: an internal transfer to a checking account at the same bank, an ACH transfer to an account at another bank, or a wire. Internal transfers are usually the fastest. ACH transfers to another bank normally take one or more business days, and some banks offer a faster option for a fee or for certain customers. Wires are fast but are the transfer type most likely to carry a fee. The exact timing and cost are in two documents: the bank's funds-availability policy and its fee schedule. Read both before you rely on the account as an emergency fund, because the question that matters is "how soon could this money be in my checking account on a Friday evening?"
Many online savings accounts have no debit card and no checks, so cash access depends on a linked checking account. If you want the convenience of a card, look at whether the same bank offers a checking account you would actually use, or keep a small buffer in your everyday checking account and treat savings as the second line. If you deposit paper checks by phone, look up the bank's mobile deposit limits and hold periods in its own disclosure. And plan ahead for large, dated payments such as a home down payment or tuition: start the transfer several business days early and confirm the receiving account's limits, so that a hold or a daily cap does not delay a closing.
Comparison
Use this worksheet for each account you are considering. Fill in the right-hand column yourself from the bank's own pages, and write the date you checked, because rates and fees change.
| What to compare | Where to find it | What to look for |
|---|---|---|
| Current APY | The bank's rate page or account disclosure | Date checked; introductory or standard rate; any balance cap or condition |
| Monthly fee | Fee schedule | Whether a fee exists and what waives it |
| Opening deposit | Account page or membership terms | Minimum to open; credit union share purchase |
| Deposit insurance | FDIC BankFind or NCUA locator | Insured charter name; $250,000 per depositor, per institution, per ownership category |
| Withdrawal limits | Deposit account agreement | Monthly cap, excess-withdrawal fee, or none |
| Transfer speed | Funds-availability policy | Business days for ACH out; any faster option and its fee |
| Access | Account features page | Linked checking, debit card, mobile deposit limits |
Fee Checklist
- Monthly maintenance fee, and the condition that waives it, if any.
- Outgoing domestic and international wire fees.
- Expedited or official check fees.
- Paper statement fee, and whether e-statements remove it.
- Excess-withdrawal fee or monthly transfer cap set by the bank.
- Inactivity or dormancy fee, and how long an account can sit unused before it applies.
Are high yield savings account interest rates guaranteed for a full year?
No, interest rates on high yield savings accounts are variable and can fluctuate daily based on macroeconomic conditions and Federal Reserve policy adjustments. The account disclosure explains how the bank may change the rate and how it notifies you; read that section before you open the account.
How does the IRS tax interest earned in a high yield savings account?
The IRS treats interest credited to an account you can withdraw from without penalty as taxable income in the year it becomes available. If you receive $10 or more of interest, you should receive Form 1099-INT, and you must report all taxable interest even if no form arrives (IRS Tax Topic 403). State rules vary.
Can a depositor lose money in a high yield savings account?
Deposits are insured up to $250,000 per depositor, per insured institution, for each ownership category if the bank is FDIC-insured or the credit union is federally insured. Balances above that in one category at one institution are not insured. Market downturns do not impact high yield savings accounts because funds are not invested in equities or volatile securities.
What is the difference between a high yield savings account and a certificate of deposit?
High yield savings accounts offer variable interest rates and complete liquidity for daily withdrawals without penalty. Certificates of deposit usually lock a fixed rate for a set term and charge an early-withdrawal penalty if you take the money out before the term ends; the penalty formula is in each bank's CD disclosure.
How many high yield savings accounts can a single person open?
There is no federal cap on how many savings accounts a person can hold, though each bank sets its own account-opening rules. Because FDIC coverage is counted per insured bank and per ownership category, spreading large balances across separately chartered banks, or across categories such as single and joint accounts, can keep more of the money insured. Check the charter names: two brands can belong to the same bank.
How long do external bank transfers take to clear?
ACH transfers to another bank usually take one or more business days, and internal transfers within the same bank are often faster. The exact timing is in the bank's funds-availability policy, which is worth reading before you count on the account for emergencies.
- Compare accounts on the APY posted on each bank's own rate page, with the date you checked it.
- FDIC and NCUA coverage is $250,000 per depositor, per insured institution, per ownership category.
- Rates are variable; check for introductory periods, balance caps and deposit conditions.
- Read the fee schedule and account agreement for wire, withdrawal and dormancy charges.
- Know how long an outgoing transfer takes before you rely on the account as an emergency fund.
Sources
- FDIC, National Rates and Rate Caps — national savings rate 0.37%, release published September 21, 2026 (read October 9, 2026).
- FDIC, Understanding Deposit Insurance — $250,000 per depositor, per insured bank, per ownership category (page last updated April 1, 2024; read October 9, 2026).
- NCUA, Share Insurance Coverage — $250,000 standard for federally insured credit unions (read October 9, 2026).
- Federal Reserve Board, press release of April 24, 2020 — Regulation D six-per-month transfer limit deleted.
- eCFR, 12 CFR 1005.6 (Regulation E) — $50 / $500 liability limits (current text read October 9, 2026).
- IRS, Topic No. 403, Interest Received — Form 1099-INT at $10 or more (read October 9, 2026).
Disclaimer
This article is general information, not financial, tax or legal advice. Rules, rates and eligibility change and depend on where a reader lives and on their own situation. Figures here are illustrative; confirm current terms with the provider or agency involved, and consult a licensed professional before acting on a decision that carries real money.